orderflow
aggregate dex
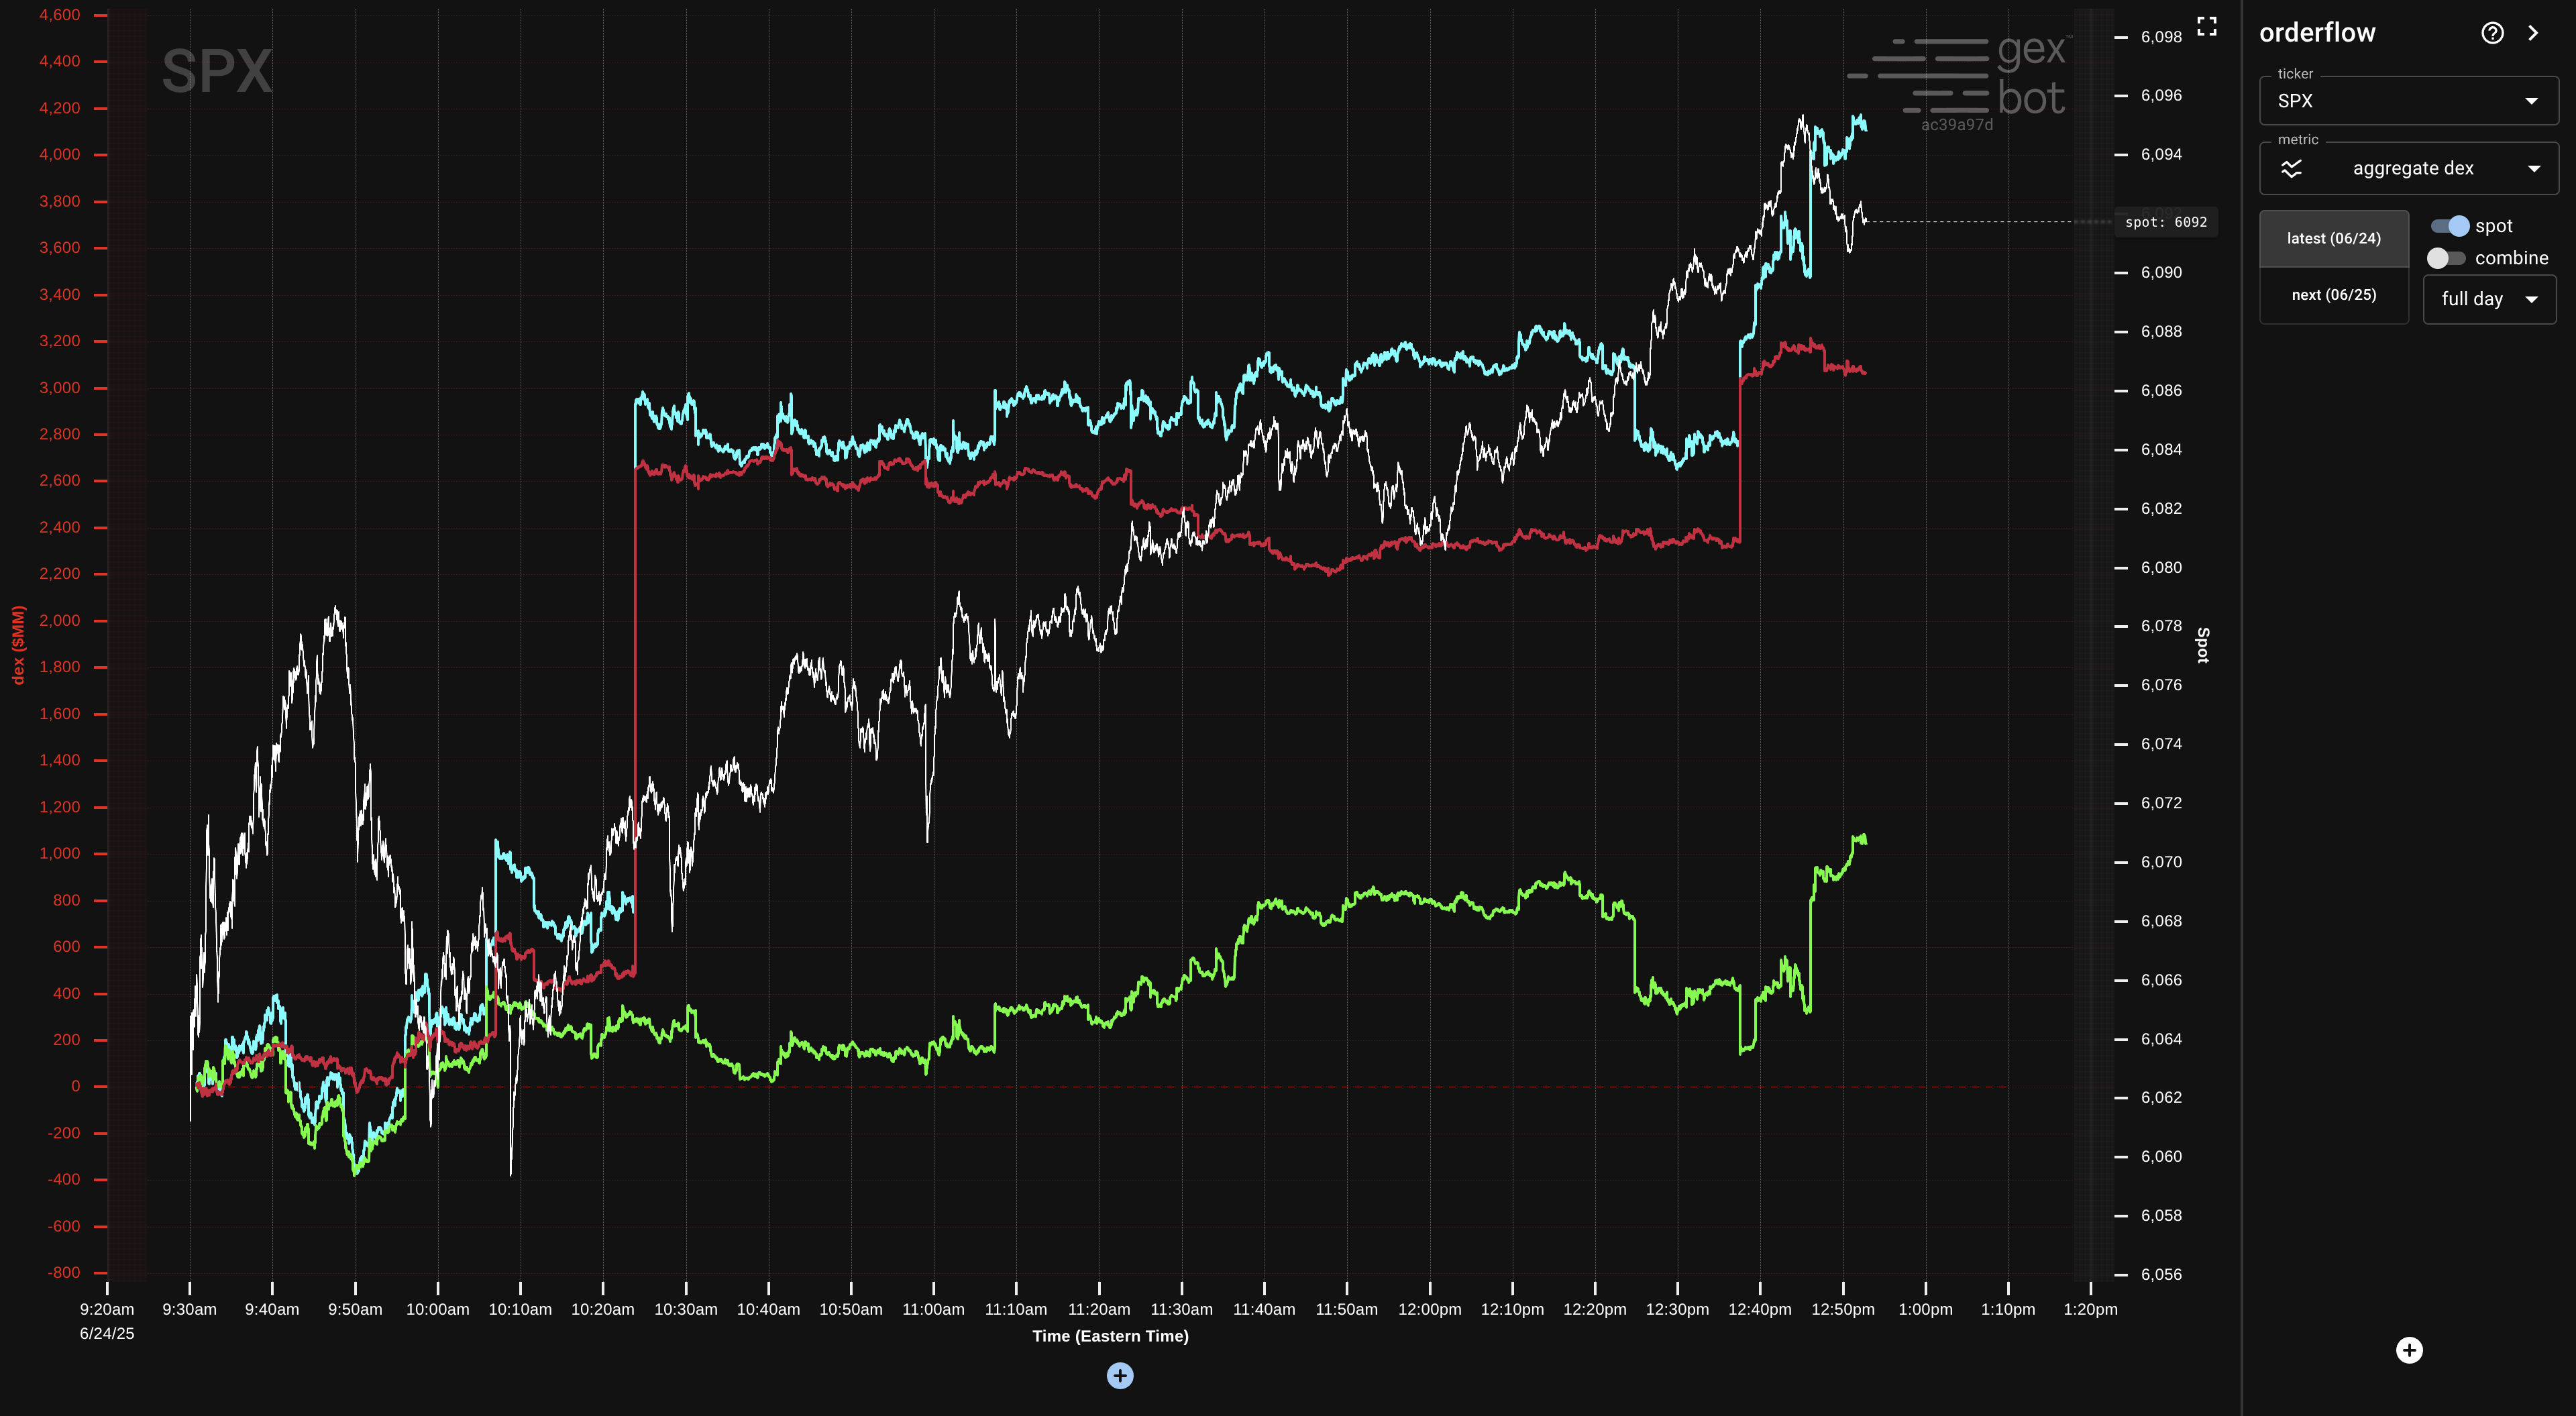
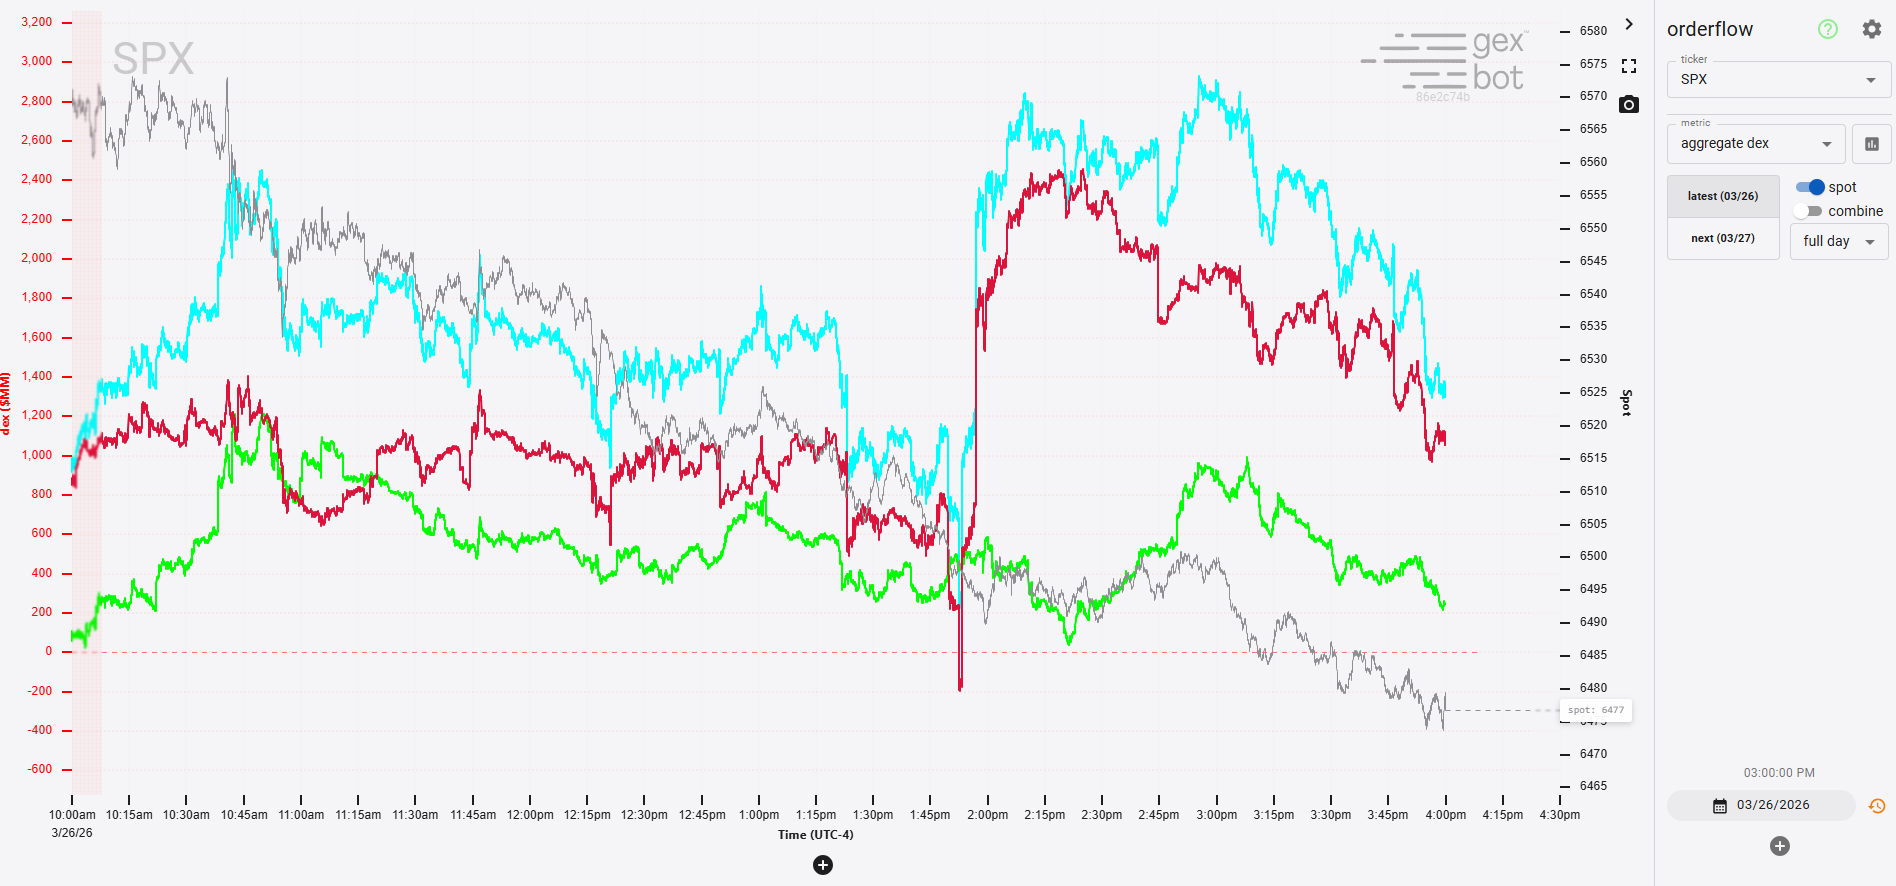
Cumulative share-equivalent delta pressure generated by options market transactions throughout the session.
API Endpoints
Access this data from the Orderflow Latest API endpoint.
Formulas & Series Breakdown
Aggregate DEX = Cumulative DEX Orderflow (Cyan)
Call Aggregate DEX = Cumulative Call DEX Orderflow (Green)
Put Aggregate DEX = Cumulative Put DEX Orderflow (Red)
Description
- Aggregate dex tells us how much buying/selling the option market has contributed over the course of the day.
- Instead of "Someone just bought/sold this many shares worth of options here", it's: "This many shares worth of options have been bought/sold so far today".
- Negative call aggdex implies more call deltas sold than bought, and vice versa for puts. So, when call aggdex is negative and put aggdex is positive, participants have been broadly shorting volatility over the course of the day.
- Different underlyings trade differently:
- In a lower volatility environment, SPX is primarily a short volatility and hedging instrument, so we often see positive put aggdex, negative call aggdex, and moderately negative net aggdex during uptrends.
- SPY options tend to trade more directionally, making divergences between SPY and SPY aggdex into particularly powerful signals.
- In high volatility environments (VIX greater than 20), SPX begins trading like SPY.