orderflow
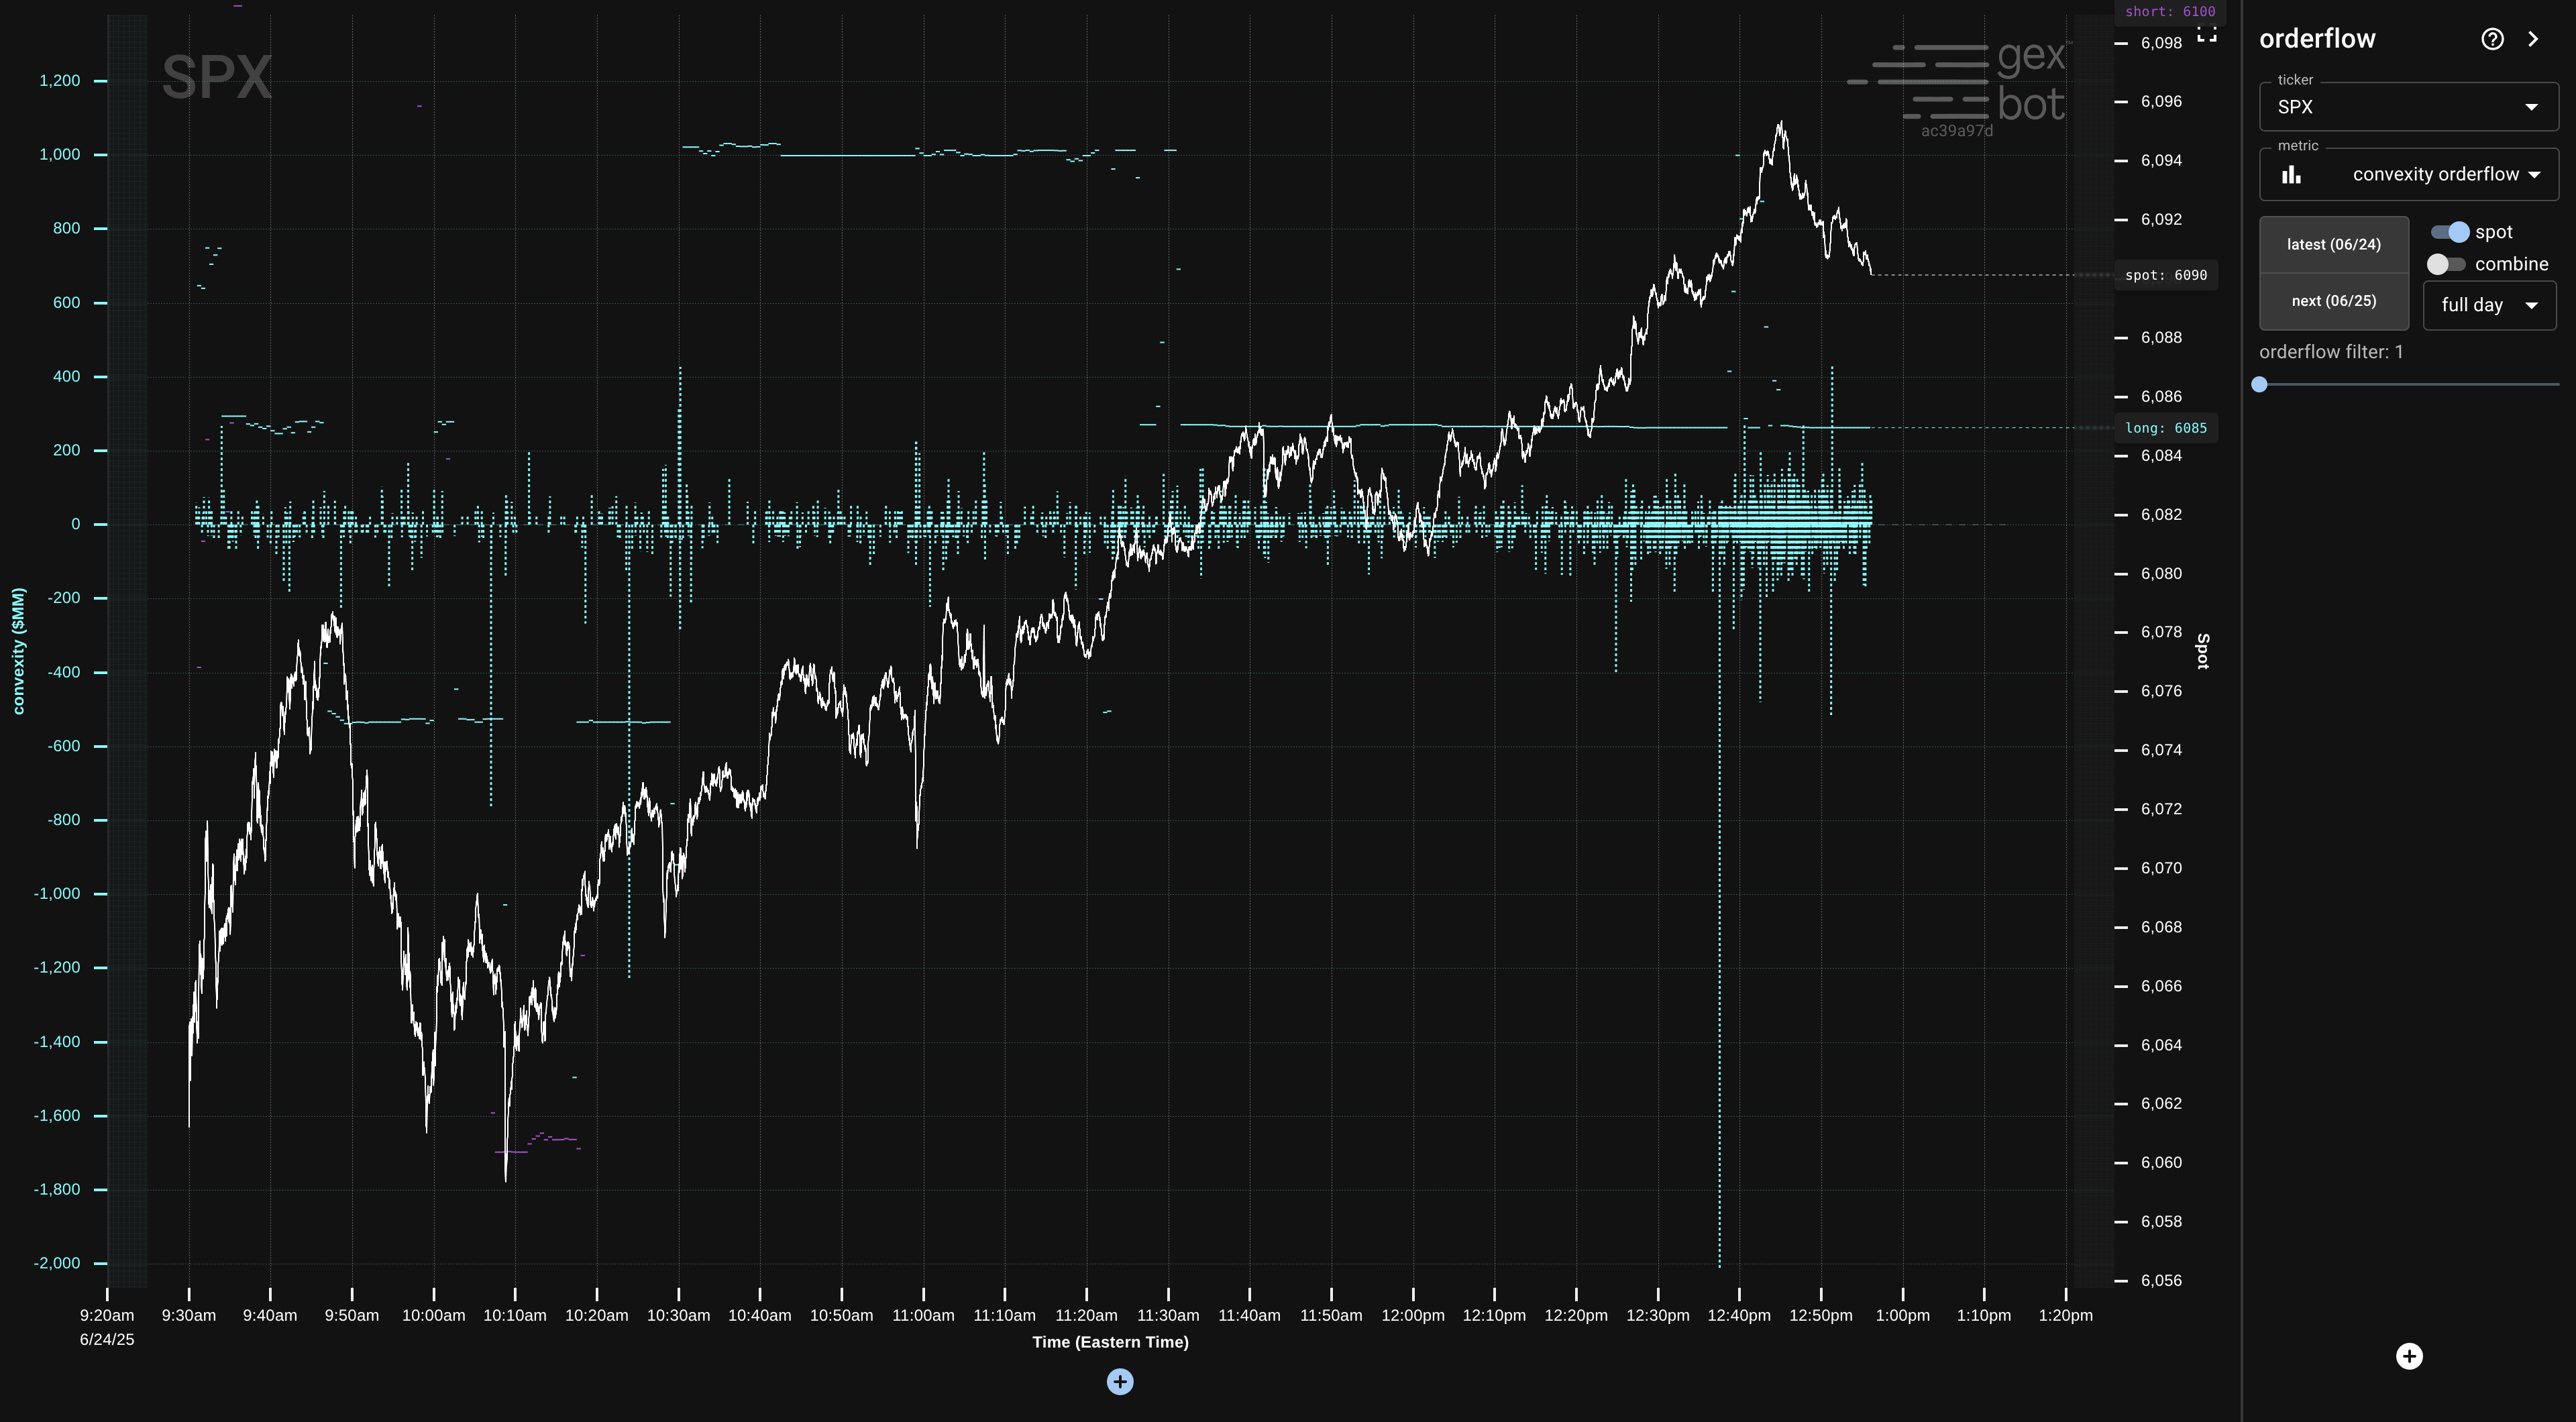
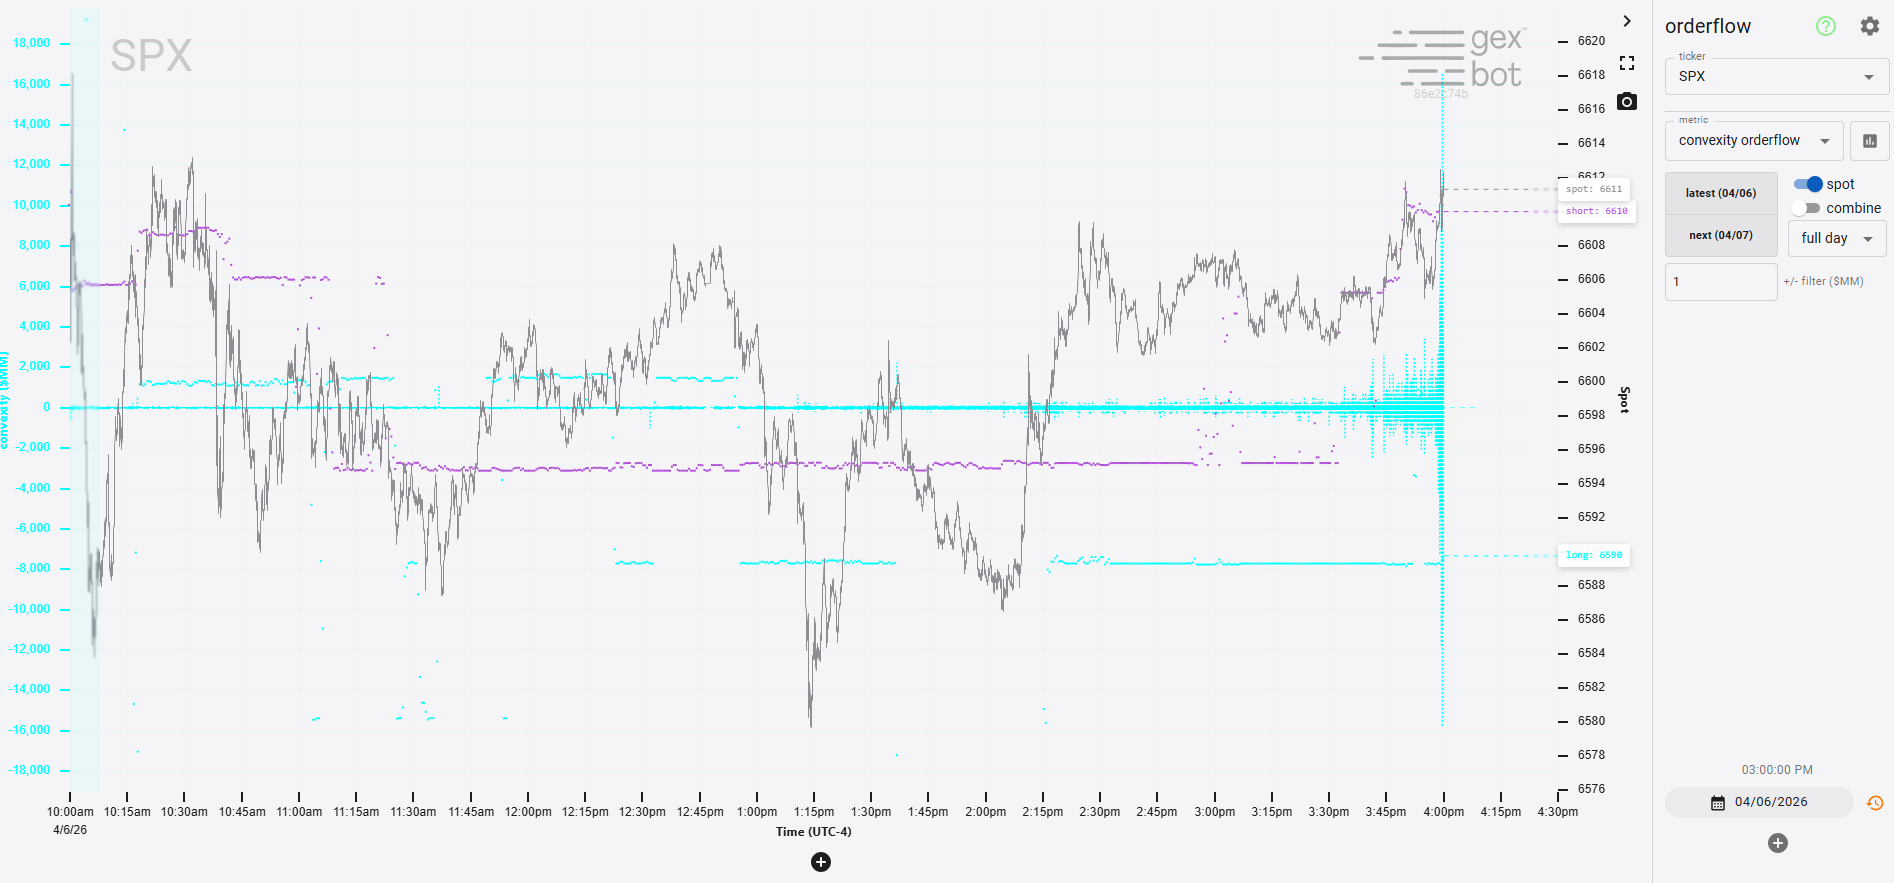
convexity orderflow
Cross-referenced against dex orderflow to read whether participants are wagering on more or less near-term volatility.
API Endpoints
Get this data from the Orderflow Latest API endpoint.
Convexity Orderflow = (Long Orderflow × GEX) - (Short Orderflow × GEX)Description
- The intended use of convexity orderflow is to cross-reference it against DEX orderflow. A transaction with positive DEX but negative convexity is a short put. If the same transaction has positive convexity, it must be a long call. In this way, one can monitor the options profile without looking at the ladder chart.
- More generally, convexity orderflow indicates when participants are wagering on more or less near-term volatility:
- Positive convexity: Participants are expecting more volatility (buying options).
- Negative convexity: Participants are expecting less volatility (selling options).
- Sell-offs are often marked by consistent positive convexity orderflow (as there is demand for volatility). Whereas grinding days and squeezes often feature consistently negative convexity orderflow.