orderflow
net convexity
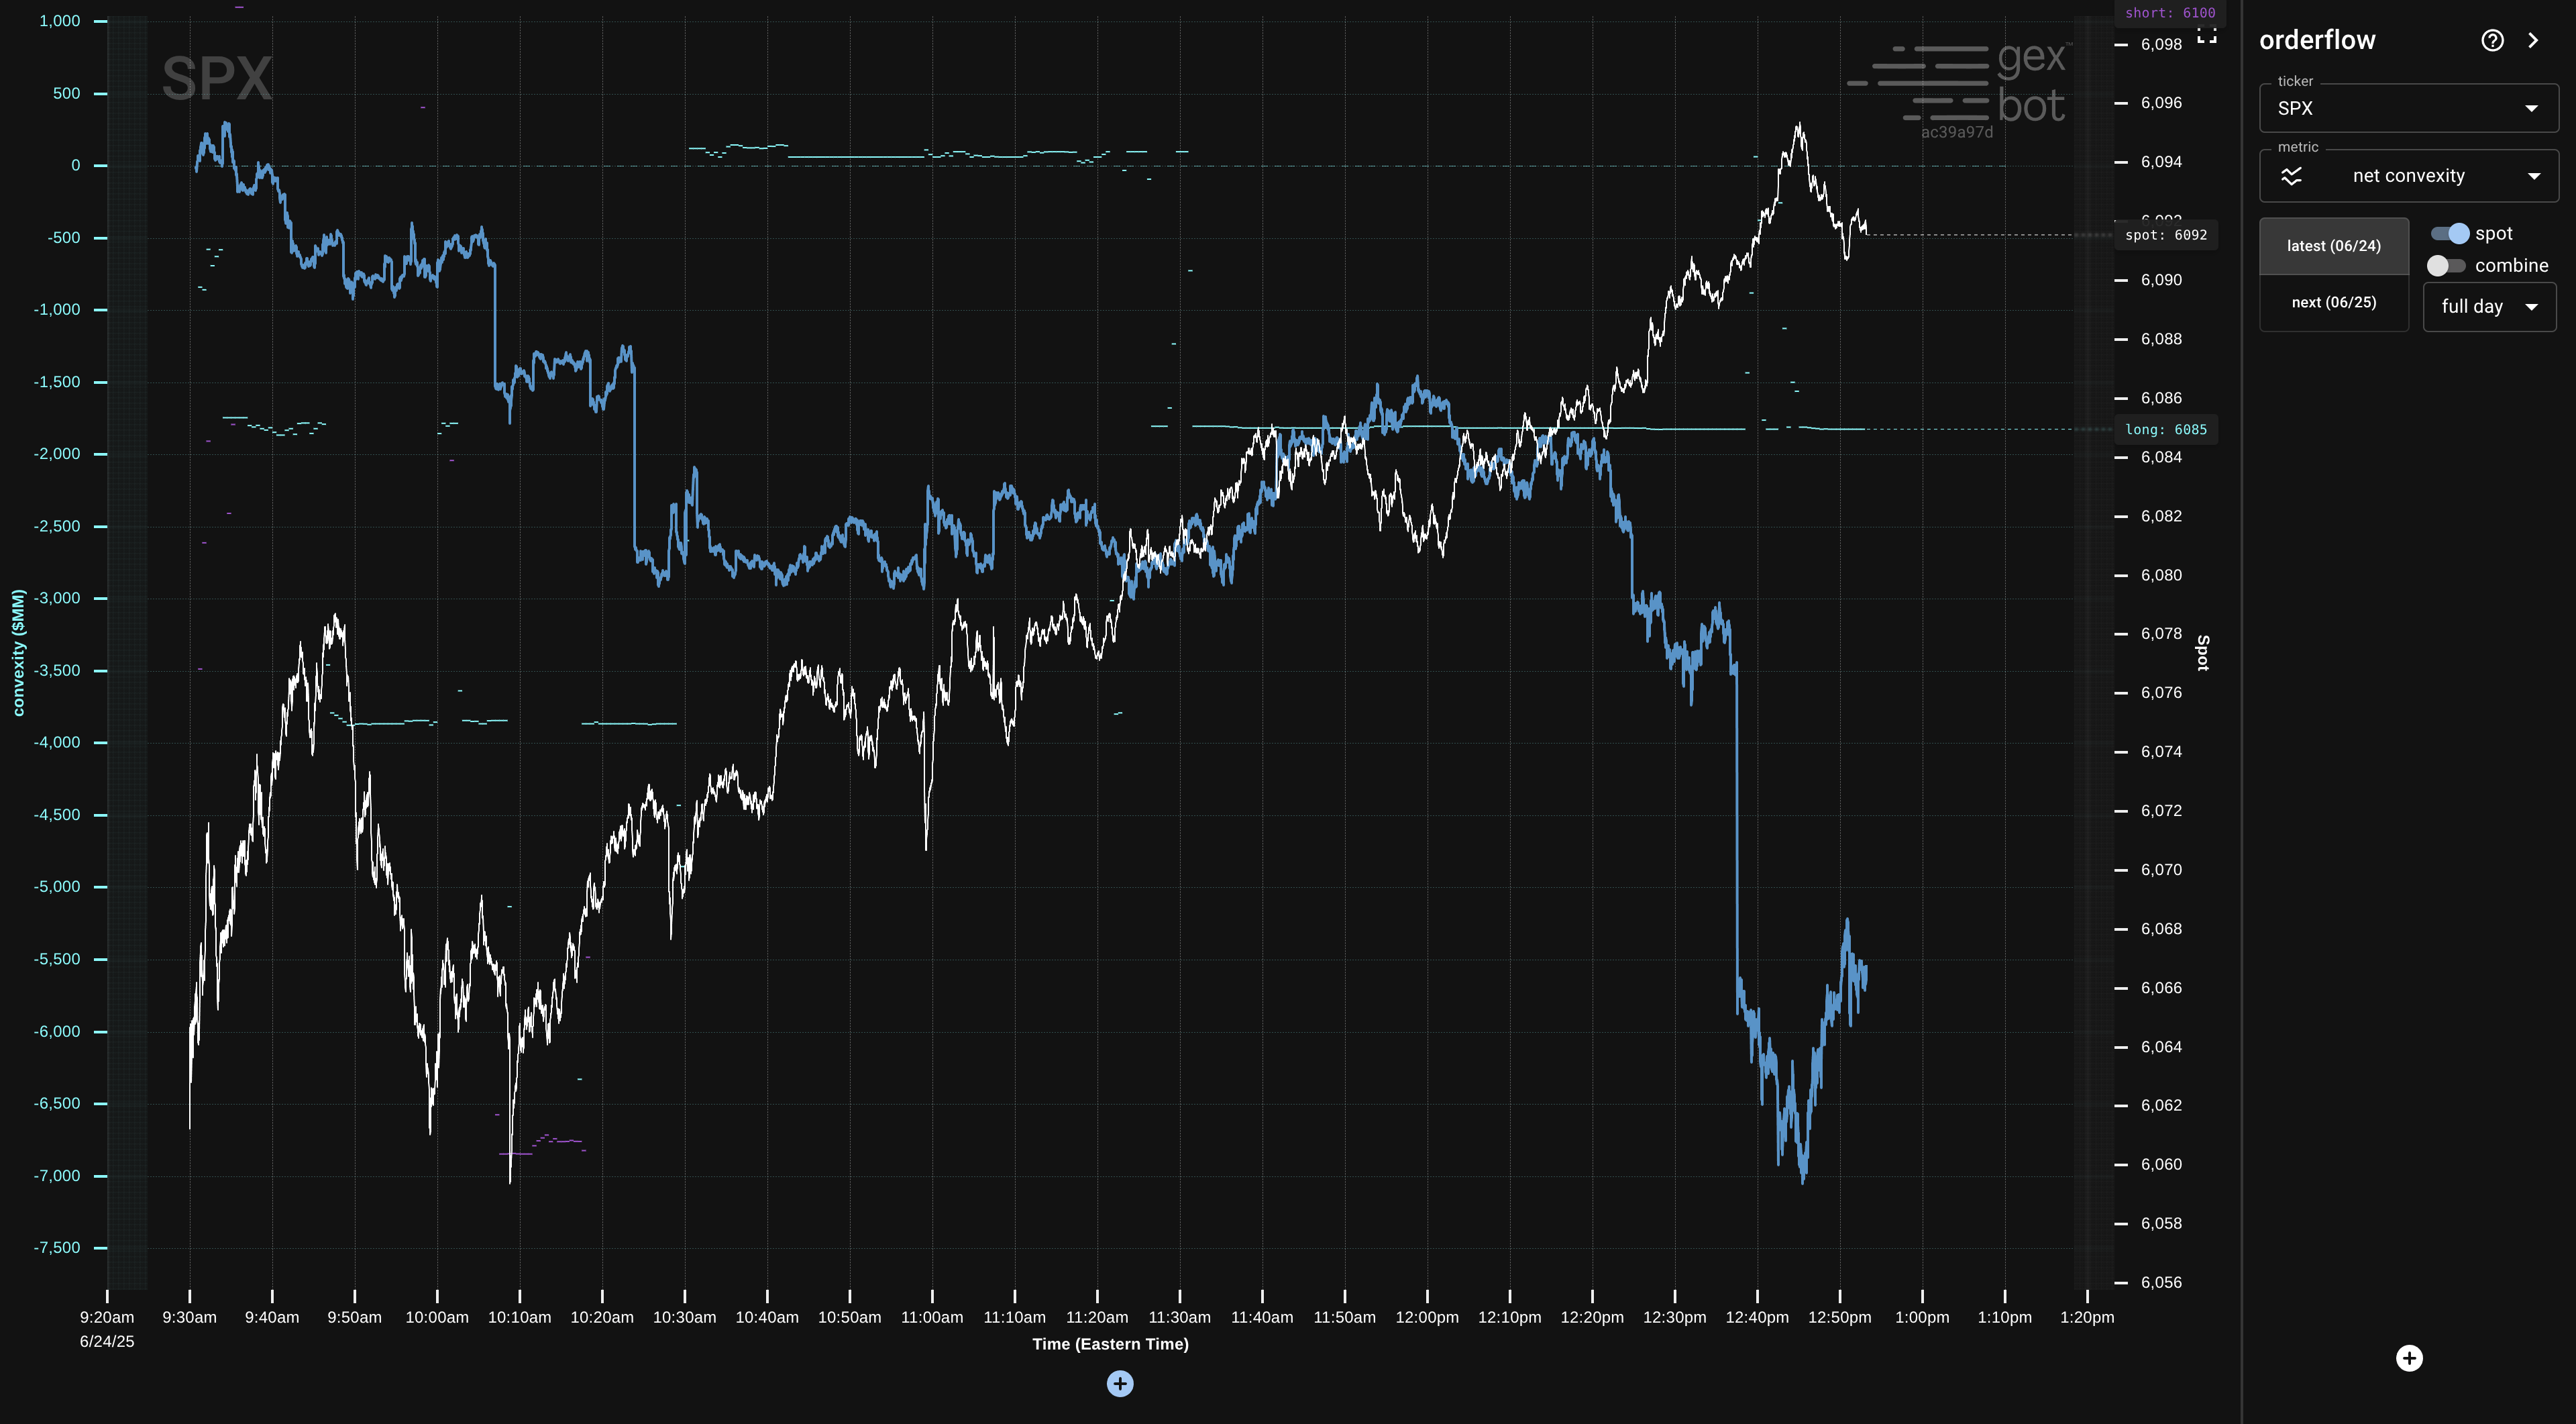
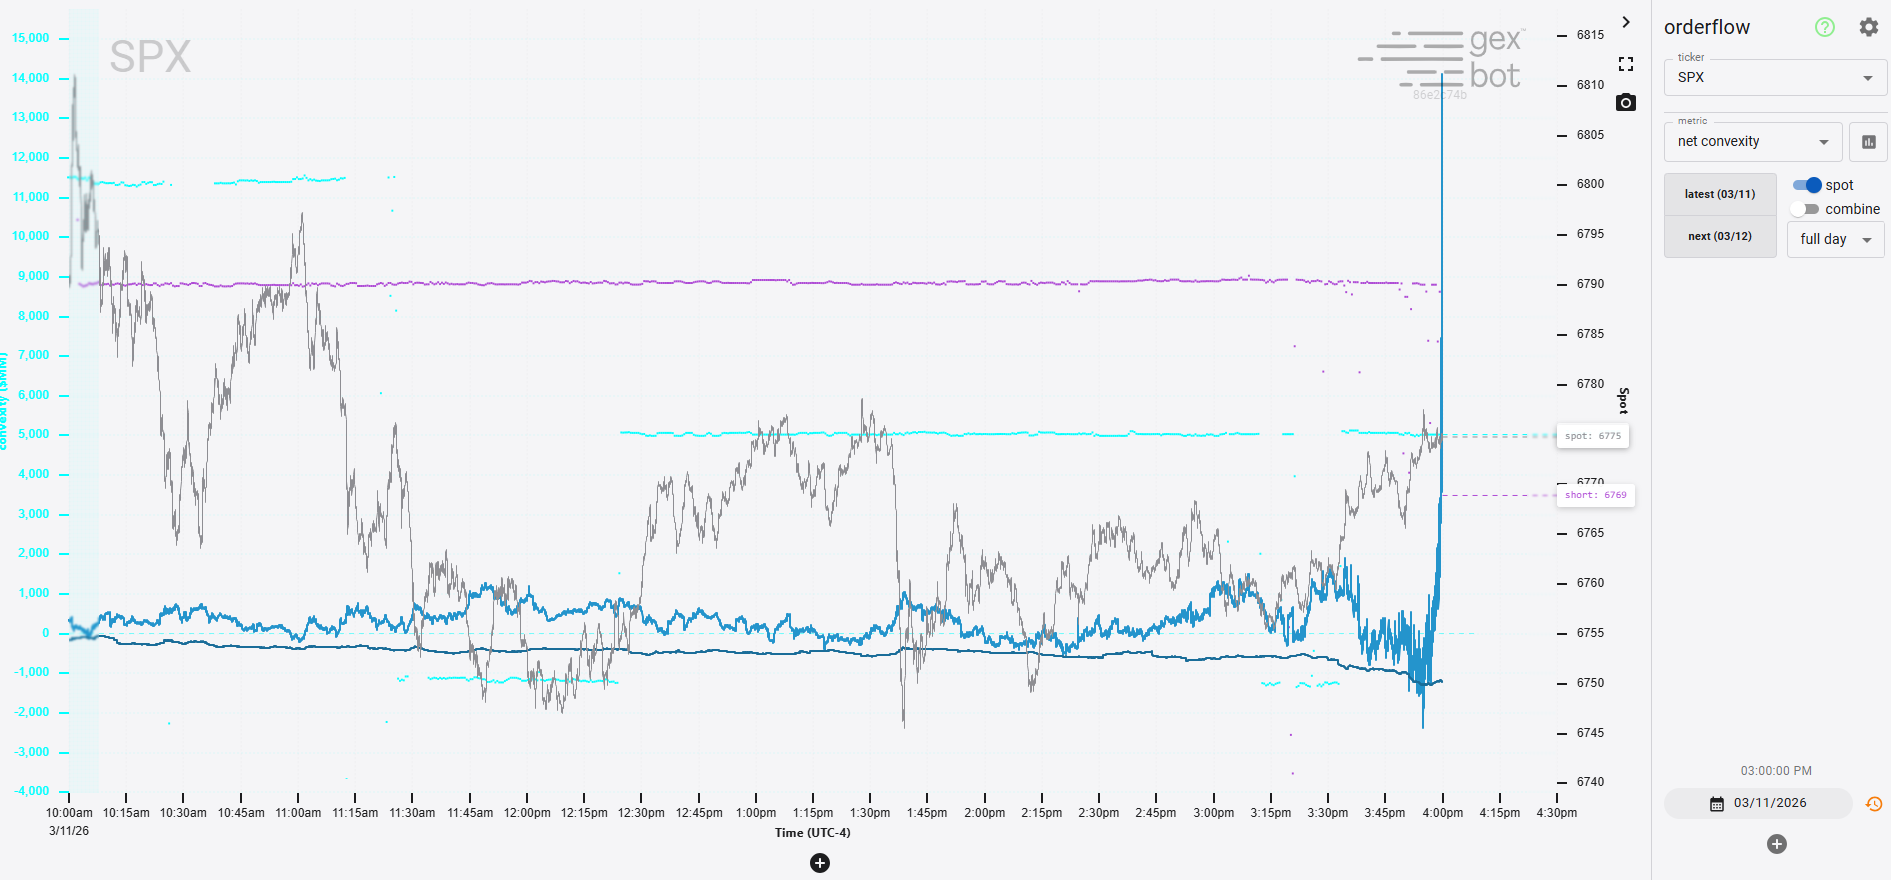
A single measure of option buying vs option selling.
API Endpoints
Get this data from the Orderflow Latest API endpoint.
Net Convexity = Total Taker Long GEX - Total Taker Short GEXDescription
- Net convexity is a measure of option buying vs. option selling across the active chain.
- Positive (high) net convexity means that participants are expecting more near-term volatility than is currently priced into the market.
- Negative (low) net convexity means that participants are expecting less near-term volatility than is currently priced into the market.
- Due to the inverse correlation between underlying price and implied volatility, low convexity is mildly constructive on underlying price. Very high net convexity, which indicates high demand for options, usually only occurs during times of panic.